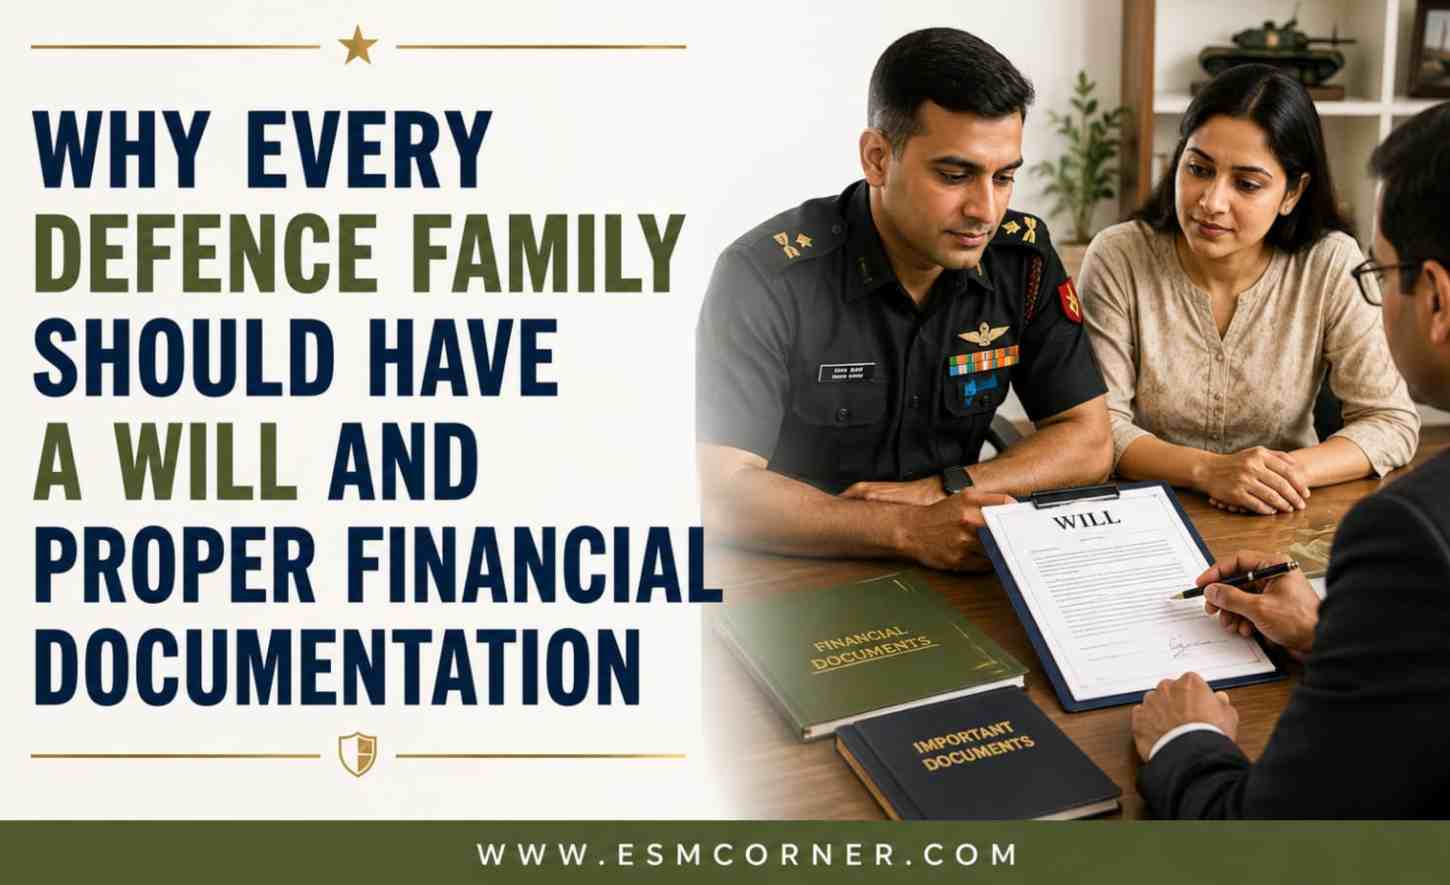
A retired Subedar spent 22 years in service. He had a pension, a PPO, two bank accounts, an LIC policy, a small plot of land, and some mutual fund investments. He was a disciplined man. His finances were in order — in his mind.
But when he passed away unexpectedly, his wife did not know which bank held which account. His son did not know where the insurance papers were kept. The PPO copy was somewhere in a tin box. The mutual fund was in a platform his children had never heard of.
Three years later, the family was still dealing with pending claims, legal notices, and avoidable disputes.
This is not a rare story. Across India, thousands of defence families go through exactly this situation every year — not because their loved one failed to build financial security, but because nobody organised or communicated it properly.
A Will and proper financial documentation are not luxuries. They are the final act of responsibility toward your family.
What is a Will? Simple Explanation
A Will is a legal written document where a person clearly states who should receive what after their death.
It can include instructions about:
- House or land and how it should be distributed
- Bank accounts and who should receive the balance
- Pension-related benefits and survivor responsibilities
- Insurance policies and claim beneficiaries
- Investments, mutual funds, and savings
- Gold, jewellery, and other valuables
- Any outstanding loans or financial liabilities
A Will does not need to be complicated or expensive to prepare. A simple, clearly written, legally valid Will is always far better than having no Will at all.
Without a Will, asset distribution falls under general succession laws — which can be time-consuming, expensive, legally complex, and often leads to family disputes that damage relationships permanently.
Why This Matters More for Defence Families
Defence service creates a specific set of financial records that are unique and sometimes complex:
- Pension Payment Order documents
- SPARSH account details
- ECHS medical scheme records
- Service records and discharge certificates
- Canteen Smart Card and related benefits
- Group insurance and service-linked insurance policies
- Army welfare fund entitlements
- Property through defence housing schemes
If these documents are scattered, undocumented, or unknown to family members — claiming these benefits after retirement or death becomes genuinely difficult and sometimes impossible without long legal processes.
The family is already dealing with grief. Financial confusion on top of that creates unnecessary trauma that can be completely avoided with simple planning.
The Difference Between Nominee and Legal Owner
This is one of the most misunderstood financial concepts in India.
Many people believe that once they have added a nominee to their bank account, insurance policy, or mutual fund — the job is done. The nominee will simply receive everything.
This is not completely accurate.
A nominee is usually a custodian — someone who holds the asset temporarily on behalf of all legal heirs. Final legal ownership is decided by the Will or, if no Will exists, by applicable succession laws among all legal heirs.
This means that without a valid Will, even if you have a nominee, the distribution of assets may still require court processes, legal heirship certificates, and family settlements — all of which take time, money, and emotional energy.
A proper Will combined with correct nominations gives your family the clearest and fastest path to accessing what you intended for them.
Documents Every Defence Family Must Organise
Every serving soldier and retired veteran should maintain a complete, organised financial file that trusted family members can access when needed.
This file should include:
- Aadhaar card and PAN card copies
- PPO number and pension-related documents
- Service records and discharge book
- All bank account details with branch information
- Insurance policy documents with claim procedures
- Property papers including registration documents
- Investment records — mutual funds, FDs, PPF, and others
- Loan documents and outstanding liabilities
- Nomination details for all accounts and policies
- ECHS card and medical entitlement documents
- Emergency contact numbers for bank, pension office, and insurance companies
This is not a one-time task. This file should be reviewed and updated after every major life event — marriage, retirement, new investment, new property, or change in family situation.
Why People Delay — And Why That is Dangerous
These are the most common reasons people postpone Will preparation and document organisation:
“I am still young and healthy.” Unexpected accidents, illness, or sudden death have no age requirement. Waiting for “the right time” means the right time may never come.
“I am not rich enough to need a Will.” Even a modest pension, one bank account, a small plot of land, and two insurance policies are enough to create serious legal complications for your family without a Will.
“My family already knows everything.” In most cases, they know far less than you think. Ask your spouse right now whether they can name all your accounts and investments. The answer often surprises people.
“There is plenty of time.” This is the most dangerous assumption of all. Legal complications after death do not respect timelines or grief.
How to Start — Simple and Practical Steps
You do not need a lawyer to start organising your financial documents. Begin today with these steps:
First, make a complete list of every financial asset you own — accounts, investments, insurance, property, and pension details. Second, collect all related documents and put them in one organised file or folder. Third, ensure your spouse or a trusted family member knows where this file is kept. Fourth, update all nominations to reflect your current wishes accurately. Fifth, write a simple Will — even a handwritten one is better than none, though a registered Will provides stronger legal protection.
For the actual Will preparation, consulting a lawyer or legal aid service is recommended to ensure it is properly written and legally valid.
Common Mistakes That Create Family Problems
- Keeping documents in multiple scattered places — Important papers stuffed in different drawers, boxes, and files that nobody else knows about.
- Never telling the spouse about investments — Many families discover accounts and policies only accidentally or never at all.
- Outdated nominations — A nomination made 15 years ago listing a parent as nominee, when that parent has since passed away, creates serious claim complications.
- Ignoring digital accounts — Online mutual fund platforms, digital banking, and email-linked financial accounts need documentation too.
- Assuming children will figure it out — Children dealing with grief should not also be forced to solve a financial puzzle under legal time pressure.
Conclusion
Building financial security through years of service, savings, and investment is a profound act of love for your family. But that security is only fully delivered if your family can actually access it when they need it.
A Will and organised financial documentation are the bridge between your life’s work and your family’s security. Without that bridge, even the most carefully built financial structure can become inaccessible at the worst possible moment.
Write the Will. Organise the documents. Tell your family where everything is.
It is not morbid preparation. It is the most responsible financial act you can do for the people you spent your entire career protecting.
READ ALSO: BEST SAFE INVESTMENT PLANS FOR RETIRED DEFENCE PERSONNEL IN INDIA – 2026
Frequently Asked Questions
Q1. What is a Will in simple words?
A Will is a legal written document where you clearly state who gets your property, savings, pension, insurance, and investments after your death. It doesn’t need to be complicated. Even a simple, properly signed Will gives your family far more clarity and legal protection than having no Will at all.
Q2. Why is financial documentation especially important for defence families?
Defence service comes with unique entitlements — PPO, SPARSH, ECHS, service insurance, welfare funds. If these documents are unorganised or unknown to family members, claiming rightful benefits after retirement or death becomes very difficult. Many widows lose entitled benefits simply because they didn’t know what existed or where documents were kept.
Q3. Is a Will necessary even for ordinary middle-class families?
Absolutely yes. Even a modest pension, two bank accounts, a small plot, and basic insurance can create serious legal complications without a Will. Distributing assets without a Will — called intestate succession — can take years, cost heavily in legal fees, and cause painful family disputes during an already emotional time.
Q4. Is nomination alone enough or is a Will still needed?
Nomination alone is not enough. A nominee is typically a temporary custodian, not the final legal owner. Final ownership is decided by a valid Will or succession laws. Without a Will, even correctly nominated assets may require heirship certificates, court orders, or family settlement agreements before full transfer happens.
Q5. What documents must every defence family organise?
PPO and pension papers, Aadhaar and PAN cards, discharge book, all bank account details, insurance policy documents, property papers, mutual fund and FD records, loan documents, updated nominations, ECHS medical documents, and emergency contact numbers. This file must be known to your spouse and at least one trusted family member.
Q6. What problems arise without proper financial documentation?
Delayed pension claims, property disputes among relatives, unclaimed bank balances, insurance settlement delays, investment claim complications, and painful family conflicts — all happening when the family is already grieving. Almost all of these problems are completely avoidable through simple, consistent documentation and a clearly written Will.
Q7. Why must nominations be updated regularly?
Old nominations may list someone who has passed away or exclude your current spouse. Outdated nominations force families through unnecessary legal processes at the worst possible time. Review and update nominations after every major life event — marriage, death of a nominee, retirement, or new investments.
Q8. Should family members know about your financial accounts?
Yes. Your spouse at minimum should know which banks hold accounts, which platforms hold investments, where insurance documents are kept, and where the financial file is stored. Many families discover accounts accidentally — or never at all — losing entitled money permanently because nobody knew it existed.
Q9. Do online investments and digital accounts also need documentation?
Yes, increasingly so. Mutual fund platforms, digital banking, and online insurance policies must all be documented. Family members should know which platforms are used and who to contact for claims. Passwords should be handled securely — perhaps in a sealed document kept with the Will. Digital assets deserve the same attention as physical ones.
Q10. What is the biggest mistake people make about Will preparation?
Simply delaying it indefinitely. People feel healthy, think they’re not wealthy enough, or assume family already knows everything. Unexpected illness or death doesn’t follow convenient timelines. Every year of delay leaves your family unprotected. Starting today — even just with an organised document list — is always better than waiting for the perfect moment.
For daily defence updates, government notifications, recruitment alerts, welfare schemes, career opportunities, education news, and other important announcements, join our WhatsApp Community. Click here to join our WhatsApp Group.